Retirement Withdrawal Planner · Excel & Google Sheets
Your 401(k) comes with a tax bill. Plan it before the IRS does.
Enter your savings once. See every year of your retirement: what to withdraw, what you’ll pay in tax, and how long your money lasts.
Roth conversions for this year must be done by December 31.
- Ready in 15 minutes
- Instant download
- 2026 IRS rules
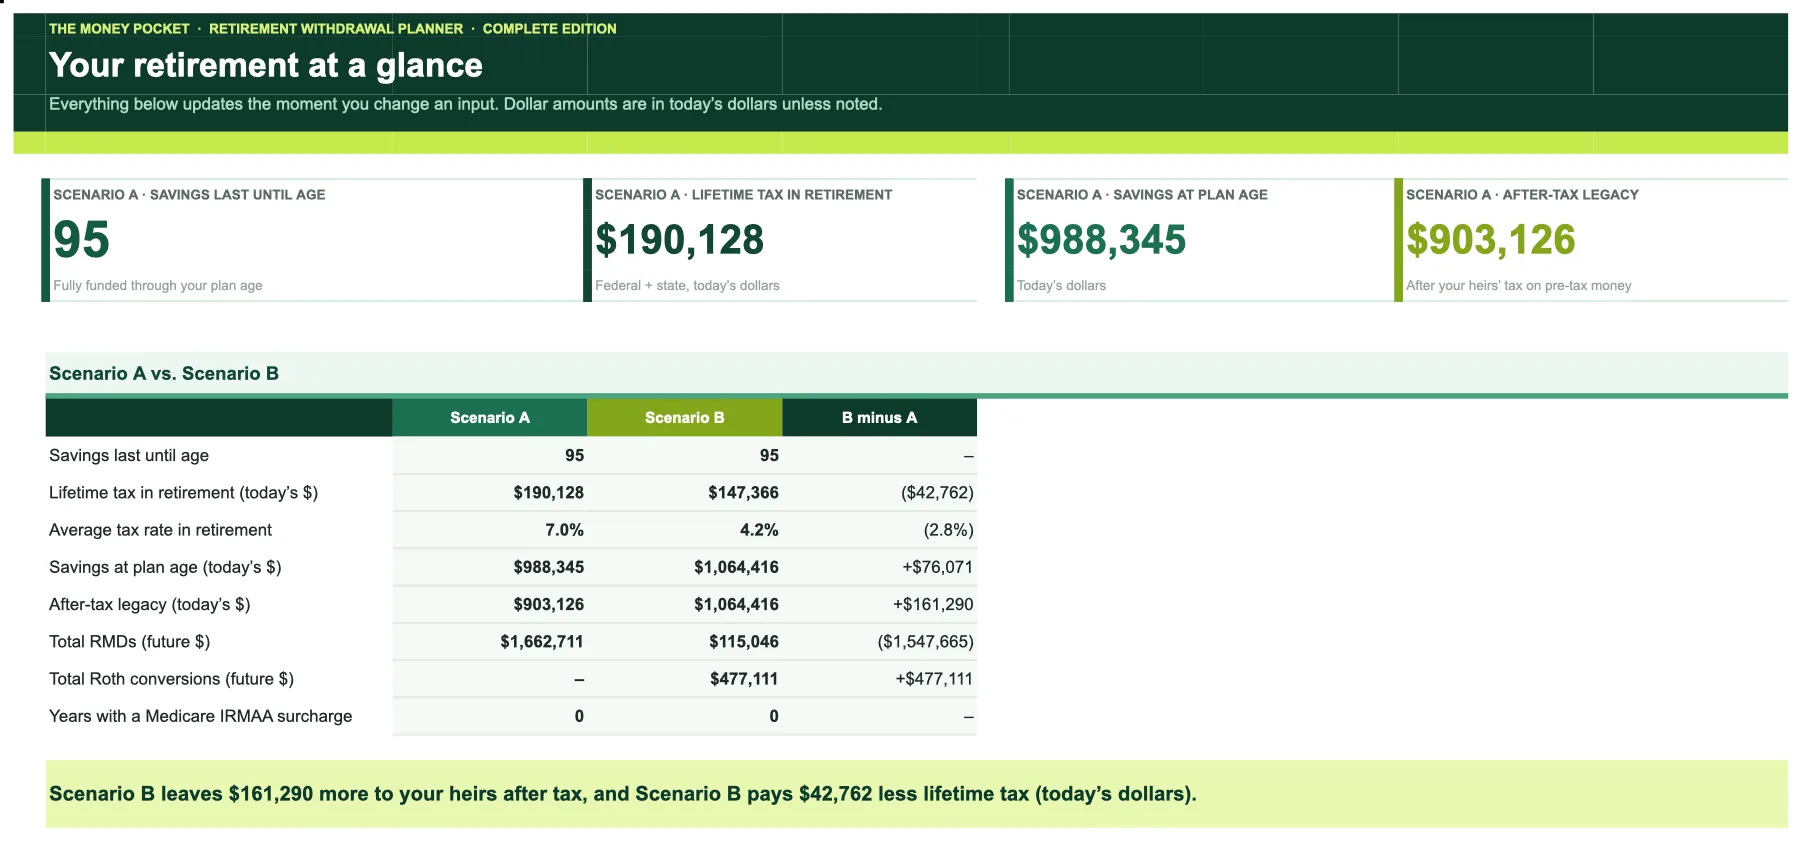
Example inside
$42,762 less tax
You need this if…
- You have $250,000+ in a 401(k), 403(b) or IRA
- You are between 55 and 75
- You don’t know what you’ll pay in tax once you retire
- Nobody has shown you your RMDs yet
The IRS already has a plan for your 401(k).
From 73 or 75, it forces money out every year and taxes it. If you don’t plan the years before, the RMDs will decide your bracket for you.
Make your own plan first.
4 answers in 15 minutes
When your money runs out
The exact age — or proof that it doesn’t.
Your tax, every year
Federal and state, from your first year of retirement to your last.
Your forced withdrawals
When RMDs start, how big they get, and the bracket they push you into.
The plan that leaves you the most
Claiming age, Roth conversions, which account first — compared side by side.
The example inside the file
Same couple. Same savings. $161,290 apart.
Plan A
Social Security at 67. No conversions.
$190,128
lifetime tax
Plan B
Social Security at 70. Convert up to the 12% bracket, 65–69.
$147,366
lifetime tax
Plan B: $42,762 less tax and $161,290 more for the heirs.
Married couple, $1.3M saved, spending $85,000 a year. Today’s dollars, straight from the workbook. Your numbers will differ — that is why you run yours.
Lifetime taxless is better
Left to the heirs, after taxmore is better
The clock is already running
These dates don’t move. Each one you miss closes a door for good.
- Dec 31Last day for this year’s Roth conversionA conversion only counts for the year it is done in. Every year you skip is one fewer low-tax year before RMDs.
- 2028The $6,000 senior deduction endsEach person 65+ deducts up to $6,000 more through 2028. After that, the same income costs more tax.
- 73 or 75RMDs start — ready or notMiss one and the penalty is up to 25% of the amount you should have taken.
- +2 yearsYour income sets your Medicare billOne dollar over an IRMAA threshold raises your premiums for a full year, two years later.
What you download
Real screenshots. Fill in the cream cells — everything else updates on its own.
The Dashboard. how long the money lasts, lifetime tax, and Scenario A vs. B.
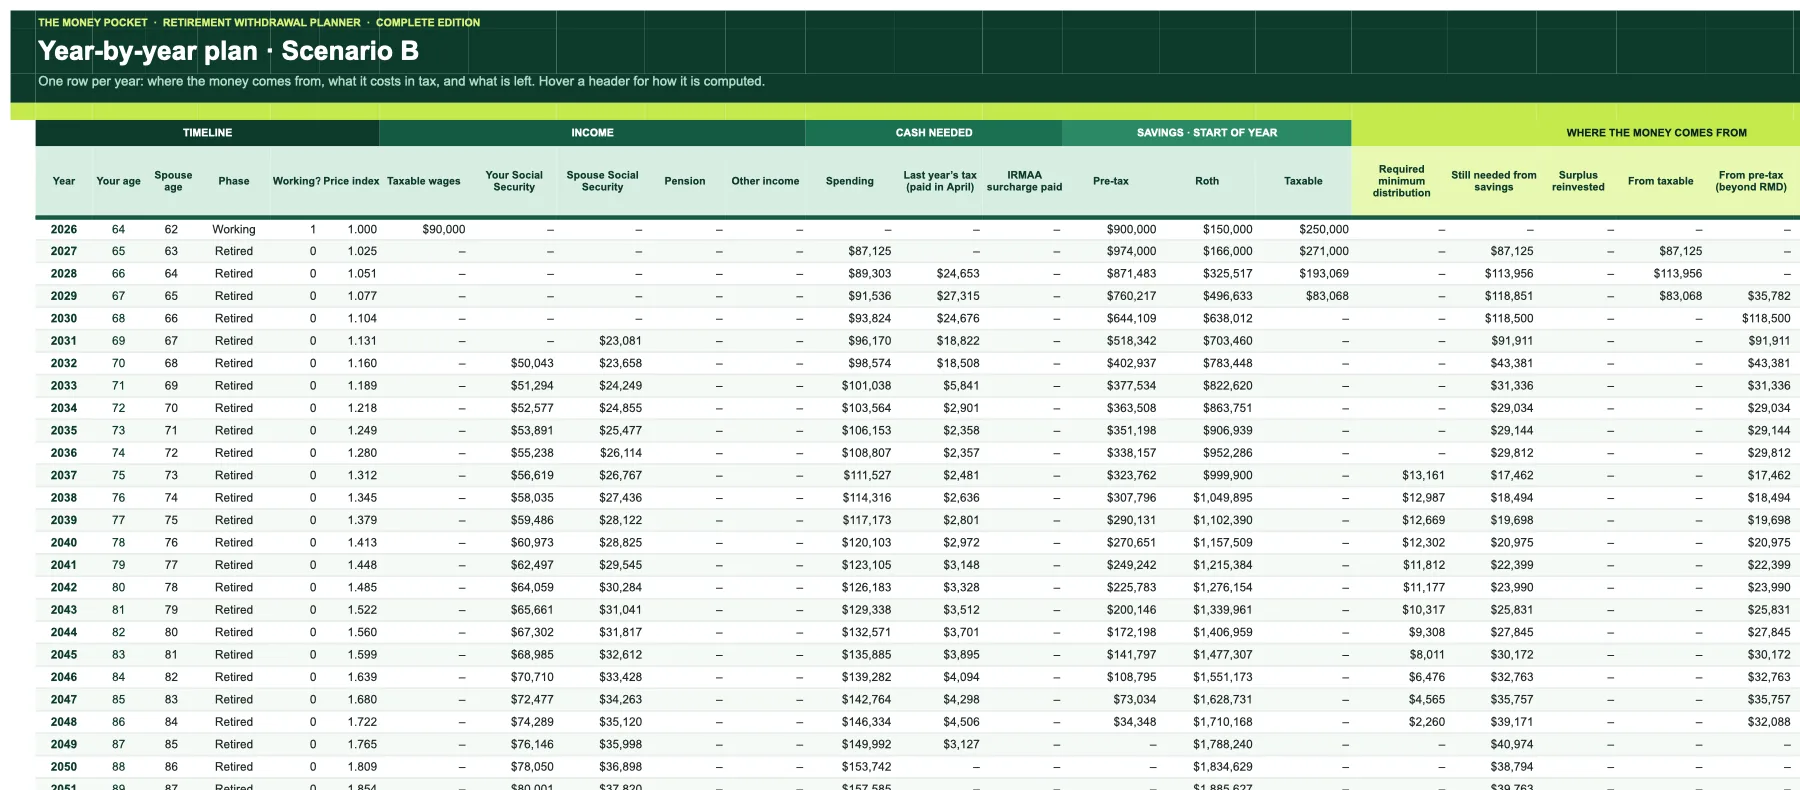
The year-by-year plan. one row per year, from your first year to your last.
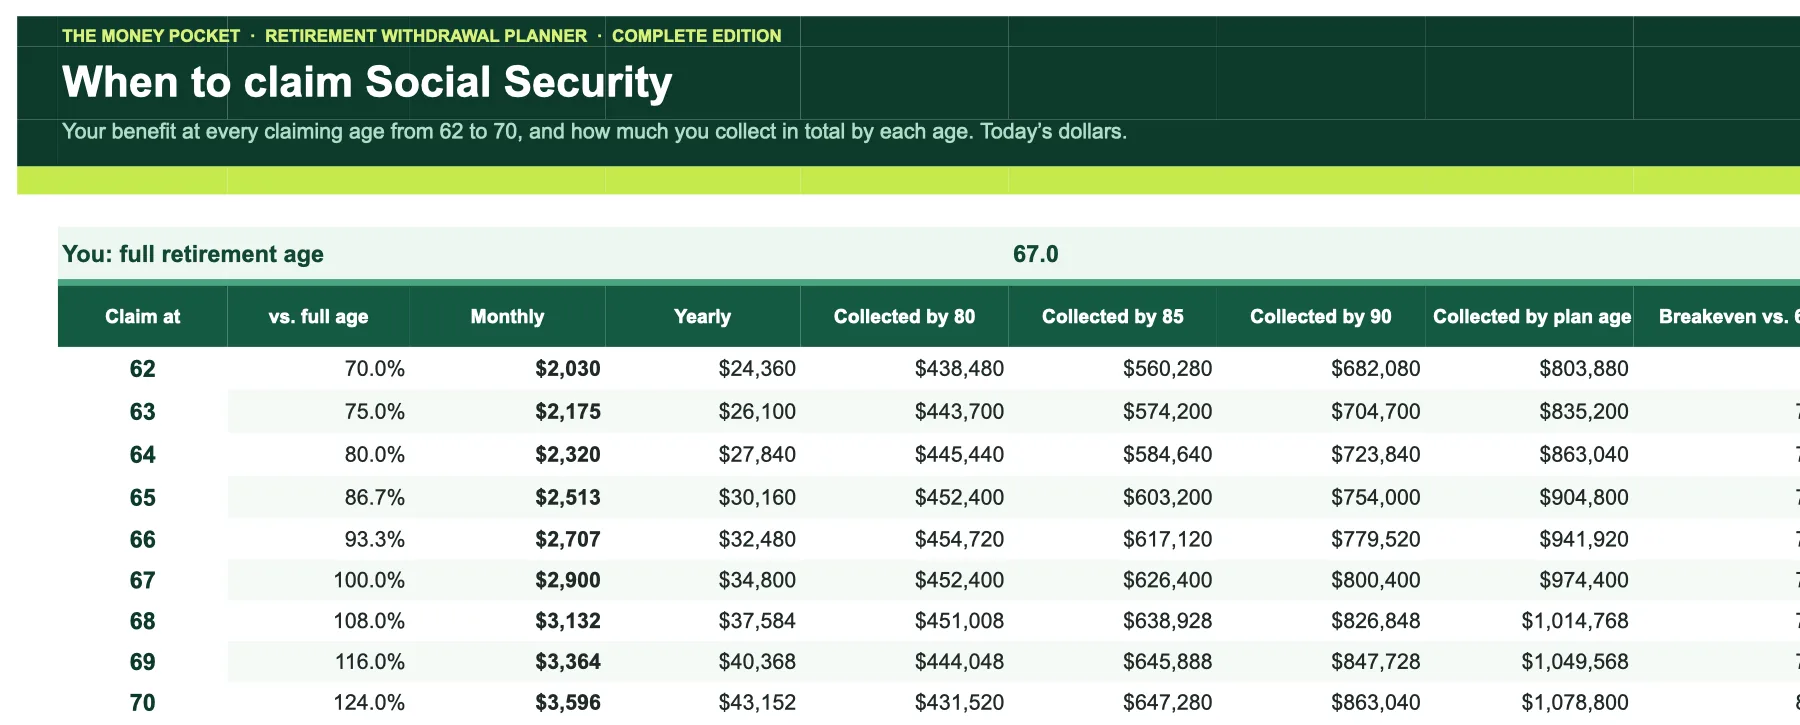
When to claim. every age from 62 to 70, totals by 80, 85 and 90, and the breakeven.
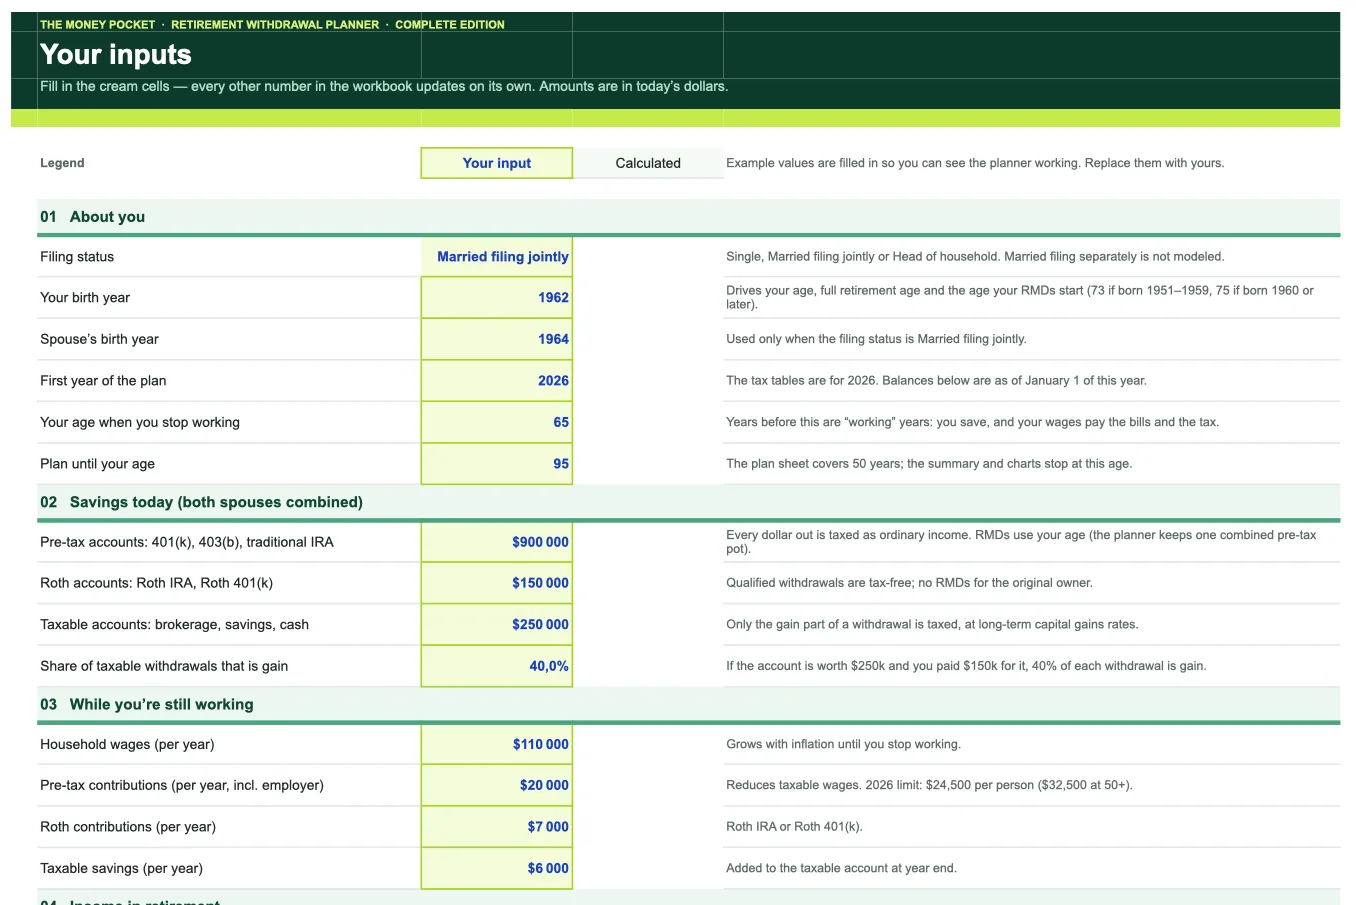
Inputs. about 30 cream cells, each with a plain-English note.
Pick your edition
One payment. No subscription. Less than an hour with a financial planner.
Retirement Withdrawal Planner
Essentials
One plan, year by year.
$34one-time
- Year-by-year plan for up to 50 years: income, withdrawals, tax and balances
- Required minimum distributions from the IRS tables (73 or 75)
- 2026 federal tax: brackets, senior deduction, taxable Social Security, capital gains, NIIT
- Medicare IRMAA surcharges, two years after the income
- Dashboard: how long the money lasts, lifetime tax, legacy
- Roth conversion planner that fills the bracket you choose
- Scenario A vs. Scenario B, side by side, with the difference in dollars
- Social Security claiming table, 62 to 70, with breakeven ages
Instant download · No subscription · 2026 tax rules
Retirement Withdrawal Planner
Complete
Test strategies side by side and keep the best one.
$39one-time
Only $5 more than Essentials for everything below.
- Year-by-year plan for up to 50 years: income, withdrawals, tax and balances
- Required minimum distributions from the IRS tables (73 or 75)
- 2026 federal tax: brackets, senior deduction, taxable Social Security, capital gains, NIIT
- Medicare IRMAA surcharges, two years after the income
- Dashboard: how long the money lasts, lifetime tax, legacy
- Roth conversion planner that fills the bracket you choose
- Scenario A vs. Scenario B, side by side, with the difference in dollars
- Social Security claiming table, 62 to 70, with breakeven ages
Instant download · No subscription · 2026 tax rules
Digital download: you get the file right after checkout, so all sales are final.
Frequently asked questions
Which apps does it work in?
Essentials or Complete?
I’m single. Does it work for me?
What if the tax rules change?
Is this financial advice?
Who sees my numbers?
Your 401(k) already has a withdrawal plan. It’s the IRS’s.
Get yours in 15 minutes.
Read before you plan
- Roth Conversion Ladder: Step-by-Step Retirement Tax Strategy
- When to Claim Social Security: 62 vs 67 vs 70
- IRA Withdrawal Tax Rules, Penalties, and Exceptions
- How Social Security Benefits Are Taxed
Just need one number? These calculators are free
- 401(k) Withdrawal Calculator: Tax & Early Withdrawal Penalty
- Roth Conversion Calculator: Tax Cost by Bracket
- RMD Calculator: Required Minimum Distributions by Age
- Social Security Calculator: Estimate Your Benefit and Best Claiming Age
- Taxable Social Security Benefits Calculator
- IRA Withdrawal Tax Calculator
For informational purposes only. The Retirement Withdrawal Planner is not tax, legal or investment advice and does not guarantee any result. It estimates outcomes from your assumptions and the 2026 federal tax rules, which can change. The example household is illustrative. See our disclosures.